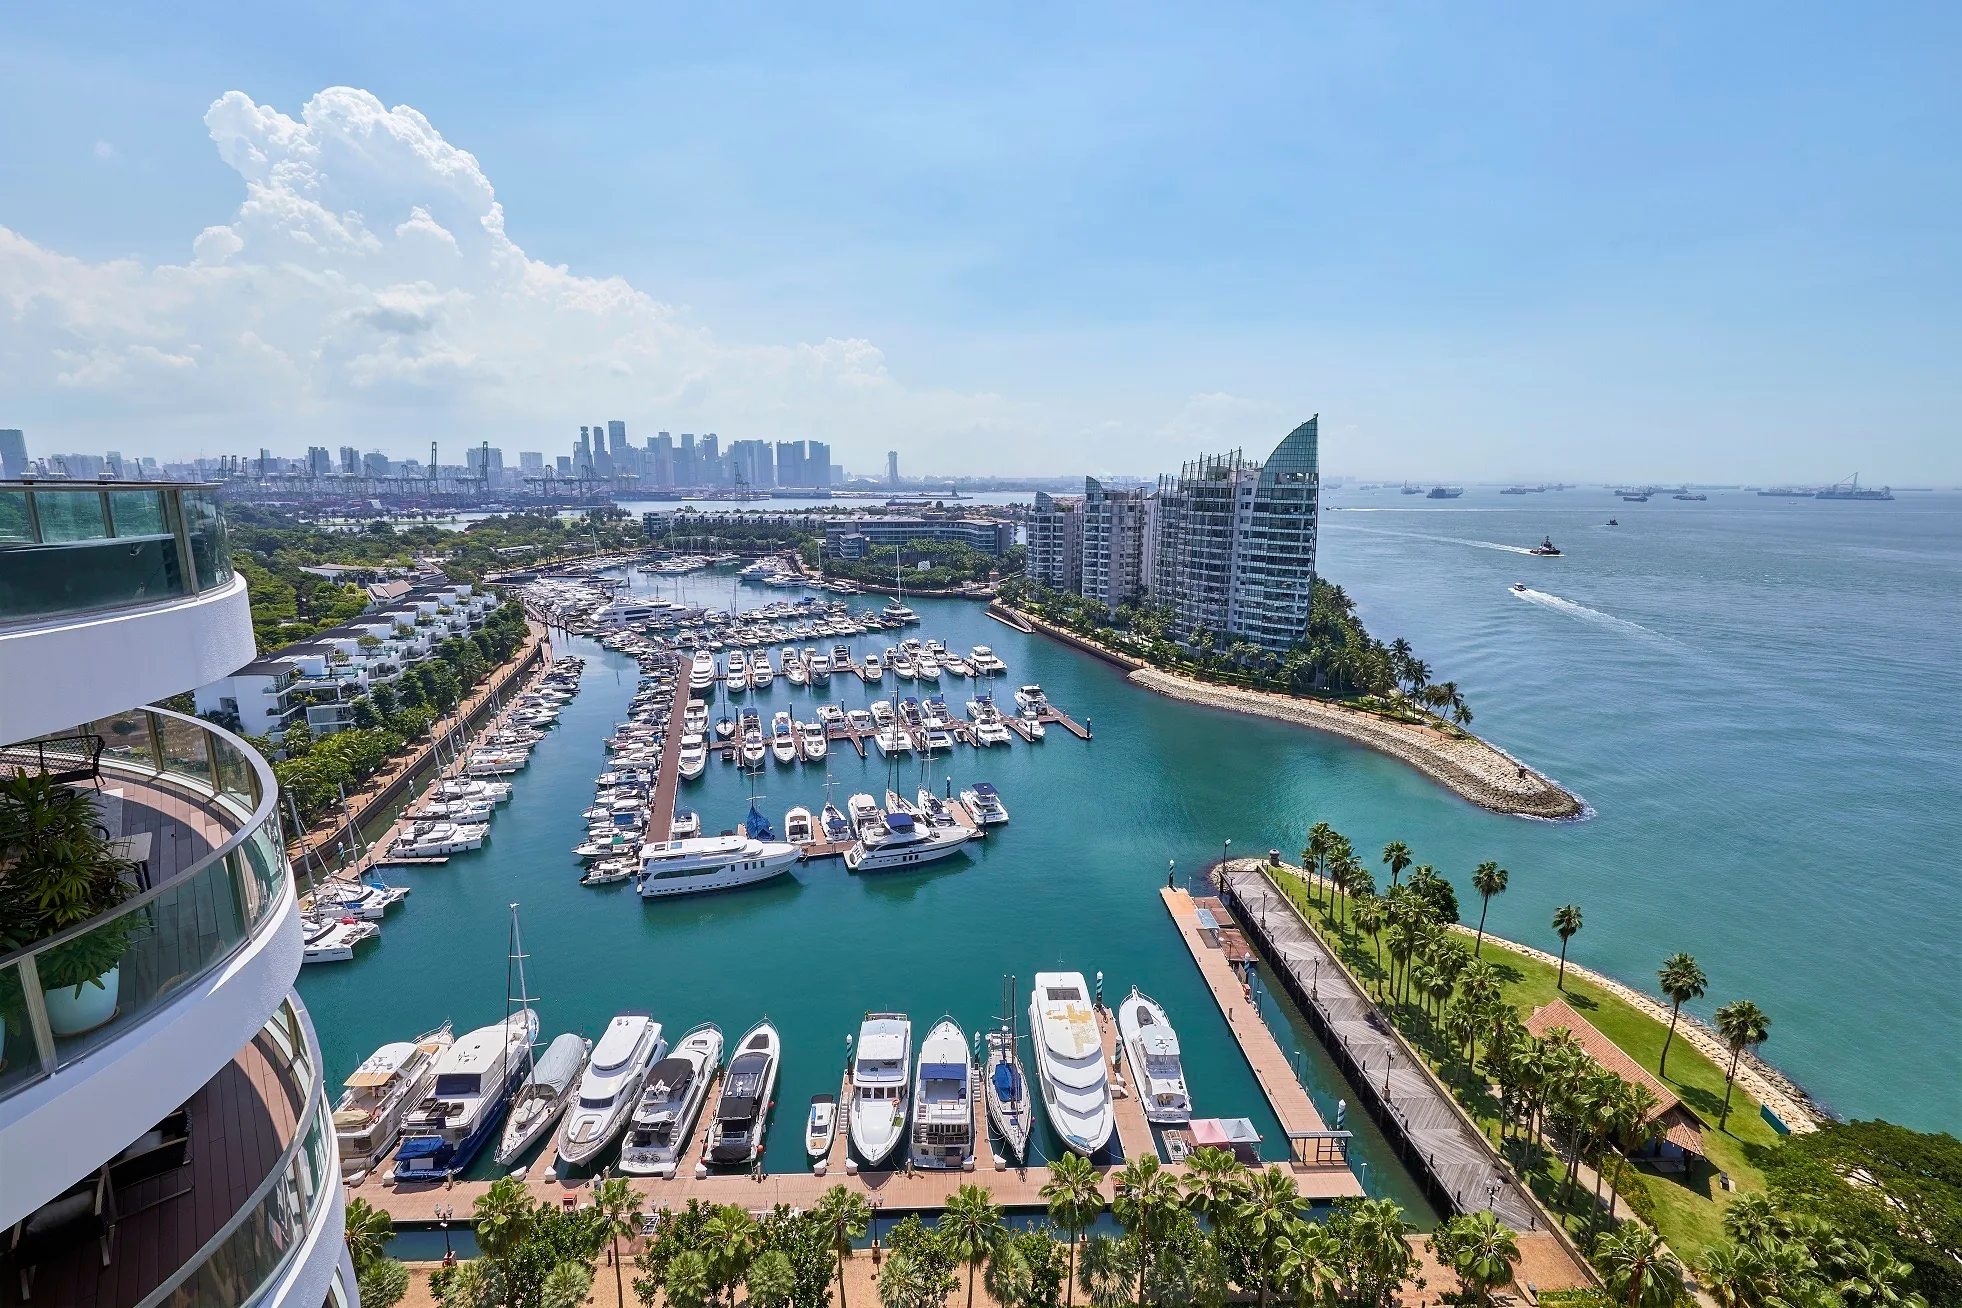
 Photograph
This TDSR calculator for Cape Royale works out the largest home loan an income can carry under the MAS Total Debt Servicing Ratio, then sets it against the loan-to-value limit on the price to show which rule decides the loan. Illustrative figure, enter your own price: the price field opens at $1,500,000, a round number that is not the price of any home at the development; the Sales Concierge sends the current price list on request. The rules behind it are explained on the housing loan information page.
Main Applicant
Counted after a 30% haircut.
Car, personal and other property loans.
Joint Applicant
Counted after a 30% haircut.
Car, personal and other property loans.
Illustrative figure, enter your own price.
Up to 35 years for private property.
Anything below 4% is tested at 4%.
Sets the loan-to-value limit.
Indicative only. A tenure over 30 years, or a loan running past age 65 (income-weighted for joint applicants), moves the loan to the lower LTV limit of 55%, 25% or 15% depending on loans outstanding, and lifts the minimum cash on a first housing loan from 5% to 10%. Where the LTV limit is lower than the TDSR figure, the LTV limit decides the loan. Banks apply their own credit policies; confirm with a bank, or ask the Sales Concierge to arrange an in-principle approval. Leave out any existing home loan that will be repaid before this purchase.
How a Loan Is Sized at Cape Royale
The bank begins with assessed income: fixed salary in full, plus variable income such as bonuses at 70% after the haircut, averaged over twelve months. Up to 55% of it may go to debt each month, so existing repayments come off first and what remains is turned into a loan at the MAS medium-term rate, the higher of a 4% floor or the loan’s thereafter rate, over the tenure chosen.
Joint buyers are assessed on their income-weighted average age. A tenure beyond 30 years, or a loan that runs past age 65 on that average, moves the loan to the lower LTV limit with a larger cash share, and the smaller of the TDSR and LTV figures becomes the loan.
The Completed-Sale Timetable at Cape Royale
Cape Royale obtained its Temporary Occupation Permit in 2013, so a purchase follows the timetable of a completed home: the building stages are already done, the instalments fall due within weeks rather than over years, and the home is ready to occupy at legal completion. The steps below are those of a sale by a licensed housing developer; the option and the sale and purchase agreement for a particular home set the exact sums and dates.
- Option to purchase: a booking fee of 5% to 10% of the price. Paid for the option, which reserves the home; the Housing Developers Rules set the booking fee for a sale by a licensed housing developer at not less than 5% and not more than 10% of the price.
- Signing the sale and purchase agreement: within the option period. The option stays open for three weeks after the buyer or the buyer’s solicitors receive the title documents and the agreement for signing; on the standard form, the first instalment brings the payment to 20% of the price, including the booking fee.
- Stamp duty: within 14 days of signing. Buyer’s Stamp Duty and any ABSD are paid to IRAS within 14 days of signing.
- Balance and legal completion: as set out in the agreement. On a completed home the remaining instalments fall due in weeks rather than years; they are paid from the bank loan, CPF and cash, and the keys are handed over at legal completion.
MAS requires a minimum cash downpayment of 5% of the price on a first housing loan at the 75% limit, which the booking fee meets. With a second or third housing loan, or at the lower limit, the loan is smaller and the cash share larger, as the housing loan page shows. Stamp duty is paid to IRAS within 14 days of signing.
Sources: the Housing Developers Rules (booking fee, rule 8; validity of the option, rule 11; the standard sale and purchase agreement), read on Singapore Statutes Online; IRAS (stamping within 14 days of signing); MAS (LTV limits and minimum cash); CPF Board (use of CPF savings), checked 27 October 2026. The option to purchase and the sale documents for a particular home govern.
Stack this result with the duty on the stamp duty calculator, or ask the Sales Concierge to go through the figures for a particular home on the current price list.
Request the Cape Royale Price List
Cape Royale is completed and open for sale. The Sales Concierge sends the current price list and the homes still open for selection in Blocks 15, 17, 19 and 25. Showflat viewings are arranged by appointment through the Sales Concierge.
Sent on request
- The current price list and the homes still open for selection.
- The e-brochure and the floor plans you shortlist.
- The stamp duty for your profile and a loan estimate from the TDSR calculator.
- A viewing appointment at a time that suits you.
Request the Price List
No obligation. The Sales Concierge responds personally to every enquiry.
Prefer to speak to someone? Call +65 6200 6220, or send a WhatsApp message to the same number.